What We Cover
- Absorption at Key Resistance Identifying scenarios where high volume occurs at a specific price level without a subsequent breakout.
- Absorption at Support and Resistance Identifying high volume clusters at key price levels that fail to produce price movement as a sign of order soaking.
- Accumulation/Distribution Divergence Measuring the relationship between price trend direction and cumulative volume flow to spot institutional positioning.
- Climax Volume Exhaustion Pattern Detecting extreme volume spikes at the end of a trend that signal potential trend reversal or temporary pauses.
- Cumulative Delta Divergence Analyzing the net difference between aggressive buyers and sellers to spot hidden trend exhaustion.
- Institutional Absorption Identification Recognizing heavy volume at support or resistance levels without price movement as signs of large orders being filled.
- Institutional Accumulation Signature Detecting large block trades or steady volume increments within the opening range that suggest directional bias.
- Intraday Volume Climax Patterns Recognizing extreme volume spikes that signal the end of a parabolic move.
- Liquidity Void Identification Locating price zones where the lack of volume history suggests rapid, uncontrolled movement.
- Opening Range Breakout (ORB) Volume Confirmation Rule A specific threshold measurement where a breakout must be accompanied by a percentage increase in volume relative to the prior five openings.
- Opening Range Breakout Volume Confirmation Using high-relative volume at the initial candle extremity to validate the direction of the intraday trend.
- Opening Range Expansion vs. Contraction Analyzing whether the volume profile supports a widening range or a narrowing consolidation phase.
- Opening Range Volatility Ratio Comparing the volume of the initial period to the average daily volume to gauge opening intensity.
- Order Flow Imbalance Measurement Analyzing the ratio of aggressive buyers versus aggressive sellers within a specific volume cluster.
- Order Flow Imbalance Ratios Calculating the delta between aggressive market buys and market sells to gauge momentum strength.
- Relative Volume (RVOL) Benchmarking Calculating current volume against a moving average of historical volume for the same time of day.
- Relative Volume (RVOL) Thresholds Setting specific multipliers against historical averages to distinguish intraday anomalies from standard flow.
- The Exhaustion Gap Measurement Quantifying the rapid decline in volume during a price move that signals an impending reversal.
- The Low-Volume Trap Identifying failed breakouts characterized by price movement that lacks a corresponding spike in volume.
- The V-Shape Recovery Volume Profile Identifying the specific volume structure required to validate a rapid trend reversal.
- The Volume Climax Reversal Rule Recognizing the spike in extreme volume that marks the final parabolic stage of a move.
- The Volume Exhaustion Fade Identifying price reversals caused by a climactic surge in volume at the edge of the opening range.
- The Volume-Price Divergence Failure Identifying price breakouts that occur on declining volume as potential bull or bear traps.
- Volume-Based Stop Loss Placement Using high-volume nodes or price-volume clusters to determine where market makers are likely to hunt liquidity.
- Volume Climax Reversal Patterns Recognizing extreme volume spikes at the end of a trend that signal exhaustive selling or buying.
- Volume-Price Divergence in the Opening Range Recognizing instances where price moves in one direction while volume trends in the opposite, signaling a lack of conviction.
- Volume-Price Divergence Patterns Spotting instances where price makes a new high or low while volume fails to confirm the move.
- Volume Profile Value Area Migrations Tracking how high-volume nodes shift vertically to identify trend persistence or exhaustion.
- Volume Spikes at Support/Resistance Analyzing high-volume absorption at key levels to determine if a level is being defended or breached.
- Volume-Weighted Average Price (VWAP) Deviation Reversion Measuring the distance between price and VWAP to identify mean reversion opportunities.
- Volume-Weighted Average Price (VWAP) Deviation Measuring the distance between the current price and the VWAP during the opening range to identify mean reversion or trend strength.
- Volume-Weighted Average Price (VWAP) Deviations Measuring the distance between current price and VWAP to identify overextended mean-reversion opportunities.
- Volume-Weighted Momentum Oscillators Utilizing indicators like the Money Flow Index to quantify the intensity of capital inflow and outflow.
- VWAP Deviation Analysis Using Volume Weighted Average Price as a baseline to measure the strength of a trend relative to average cost.
Volume Is Half of What the Range Is Made Of
An opening range is normally described by two numbers and nothing else. Those two numbers say how far price travelled and say nothing at all about how much business was done getting there. A range built while heavy volume changed hands and a range built while almost nobody traded can look identical on a price chart and behave in opposite ways once the period ends. Reading the participation that formed the range is the cheapest way to know which of those two sessions is actually in front of you.
Front Loaded, Then What
Almost every session opens with a burst as the overnight backlog clears, so the first minutes carry heavy volume regardless of what kind of day it turns out to be. The informative part is the stretch after that burst. Participation that decays steadily suggests the early imbalance has been worked through and the auction is settling. Participation that stays elevated, or fades and then builds again before the period closes, suggests the disagreement is unresolved. The shape of that curve matters more than the total sitting underneath it.
Expansion Is the Confirmation, Not the Trigger
A break that holds usually arrives with a step change in participation rather than a gentle increase. New orders appear because the level was crossed, which is a different thing from price drifting through a line while the same handful of participants keep trading with each other. The awkward part is timing. The expansion becomes visible slightly after the break, so the confirmation lands after the decision point rather than before it, and any rule built on it has to account for that gap honestly.
Thin Breaks and Their Habits
A break carrying no more volume than the range itself is not a failed break, but it tends to behave in recognisable ways. Price often extends a short distance, stalls without follow through, and returns inside the range, sometimes taking out the entry on the way back. Nothing in the price action at the moment of the break distinguishes it from a stronger one, which is precisely why the volume reading earns its place. It is a probability adjustment rather than a filter that eliminates anything outright.
Following Volume Through a Session
The articles here stay on volume and its relationship to the opening range: what participation during formation says about the quality of the levels it produced, what a genuine expansion at the break looks like and when it becomes measurable, and what usually follows when price leaves the range without any increase in business at all. Entries, stops and targets are separate subjects and are left alone, because volume is a large enough topic on its own to be worth reading properly.
Latest Guides
Price leaves the range, the bar looks exactly like the one in the textbook, and the volume underneath it is no heavier than anything that came before. This happens often enough to deserve its own description rather than being treated as an odd exception. The chart is telling a story about conviction that the participation figures are not backing up.
What a Thin Break Actually Means
Price needs only one willing counterparty to move. When resting interest at the edge of the range is sparse, a modest amount of buying can lift price through the high without anything of consequence happening underneath. Nobody arrived. Nobody was forced to respond. The level was crossed because it was cheap to cross, not because a fresh population of participants decided it mattered.
This is common at particular times. Sessions before a holiday, the quieter stretches of the year, instruments whose main participants are trading somewhere else that morning. It also happens on ranges whose edges were never really tested during formation, since a level nobody defended has no accumulated orders sitting at it waiting to be triggered.
The Usual Sequence
The recurring pattern runs roughly as follows. Price extends a modest distance beyond the edge, moving easily because nothing is opposing it. The move then stalls, not because sellers appeared but because the buying that produced it simply finished. With no continuation and no new interest, price drifts back toward the range, frequently re-entering it, and often takes out a stop placed just inside on the way through.
The uncomfortable part is that stop. A thin break commonly travels far enough to look like it is working and to invite an entry, then reverses without ever producing the acceleration that would have justified staying in. The loss comes from a move that never went against the position violently. It just failed to go anywhere at all.
Price Action Alone Will Not Tell You
There is no bar shape that distinguishes a thin break from a heavy one at the moment it happens. The close beyond the level, the size of the bar, the clean push away from the edge, all of it can be produced by either. That is the whole argument for looking at participation rather than form. The price chart at the break shows what happened. The volume shows how many people were involved in making it happen, and only one of those two is a clue about what comes next.
The same caution applies to the retest that often follows. A retest on thin volume that holds is weaker evidence than it appears, because holding a level nobody is testing seriously is not much of an achievement.
Handling It Rather Than Avoiding It
Refusing every thin break is one answer and not an unreasonable one, particularly for a rule set that takes a single trade per session and can afford to be selective. But thin breaks do sometimes run, and a session that starts quietly can turn busy when something lands later in the morning, so a hard rejection gives up real trades along with the poor ones.
The middle position is to treat the trade differently rather than skip it. Smaller size, a target set closer in, an intention to be out if the move stalls instead of waiting for the stop to make the decision. The premise of a breakout is that other participants join. When they have visibly not joined, holding for a full extension is asking the market for something it has given no sign of being willing to provide.
Keeping the Observation Honest
It is worth writing down how each thin break resolved rather than trusting a recollection of them. The ones that failed embarrassingly are memorable and the ones that quietly worked are not, so an unrecorded impression drifts toward whichever outcome was more annoying at the time. A short note on each break and the participation behind it accumulates into something more reliable than a feeling, and it describes the instrument you actually trade rather than the market in general.
The phrase heard most often about breakouts is that they should come on increased volume. It is true enough to be worth saying and vague enough to be almost unusable as stated. Increased compared to what, measured over what window, and visible at what point relative to the moment you actually have to act. Those three questions are where the idea turns into something workable.
A Step, Not a Slope
The expansion worth paying attention to is abrupt. Participation through the range was running at some level, price crosses the edge, and the next intervals carry a visibly different amount of business. It reads as a step in the volume histogram rather than a gradual incline.
The mechanism is straightforward. The level being crossed is where other people were also watching, holding resting orders, or waiting to be convinced. Crossing it brings in participants who were not trading a moment earlier. A slow rise in volume as price approaches the edge is a different animal. That is the same population trading more actively, not a new one arriving, and it often reflects anticipation rather than commitment.
Compared to the Range, Not to the Open
The comparison that makes sense is against the volume the range itself was carrying, and specifically the quieter middle of the formation period rather than the opening burst. The first minutes of a session are heavy for reasons unrelated to any range, and measuring a break against that peak makes nearly every break look weak.
Measuring against the settled portion of formation sets a fairer bar. If business at the break is running clearly above what the range had been absorbing, something changed. If it is running at about the same rate, price crossed a line and nothing else happened, whatever the chart looks like.
The Timing Problem Nobody Solves
Here is the honest difficulty. The expansion is only measurable once some of it has already occurred, and by then price has usually moved past the level. Waiting for a completed interval of confirmed heavy volume means entering worse, sometimes considerably worse, than the break itself. Acting at the break means acting before the confirmation exists.
There is no clever resolution. There is only a choice about which cost to pay, and it should be made in advance rather than improvised. Some traders take the break and use the volume reading afterwards as a reason to manage the position more or less aggressively. Others accept the worse price in exchange for a higher proportion of breaks that continue. Both are coherent positions. Switching between them according to how the current trade feels is not.
Expansion Without Follow Through
A genuine surge in participation at the break does not guarantee continuation, and it is worth being clear about why not. Heavy volume means many contracts changed hands, and every one of them required a buyer and a seller. A large expansion where price barely progresses means the arriving orders are being met in full by someone on the other side.
That is a different picture from a large expansion where price travels steadily while it happens. The pairing to watch is volume together with distance covered. Heavy business and easy movement suggests one side is unopposed. Heavy business and stalled price suggests the break has walked into supply that was waiting for exactly this, which is a common way for a technically valid break to finish back inside the range.
Using It Without Overweighting It
Volume expansion is a probability adjustment. It shifts how much confidence a break deserves, it does not sort breaks into real and fake, and any rule that treats it as a binary gate will reject perfectly good breaks on thin days and wave through poor ones on busy days. Held loosely, as one input read against the instrument's own recent behaviour, it is one of the few things available at the moment of the decision that says anything at all about whether other participants agree with the move.
Volume during the opening period tends to be glanced at once and then forgotten as soon as the two lines are drawn. That is a waste. The range and the volume that produced it are one object, not two. An identical high and low can come from heavy sustained participation or from almost nobody trading, and those two sessions do not behave the same way once the period closes.
Participation Is Not the Same as Movement
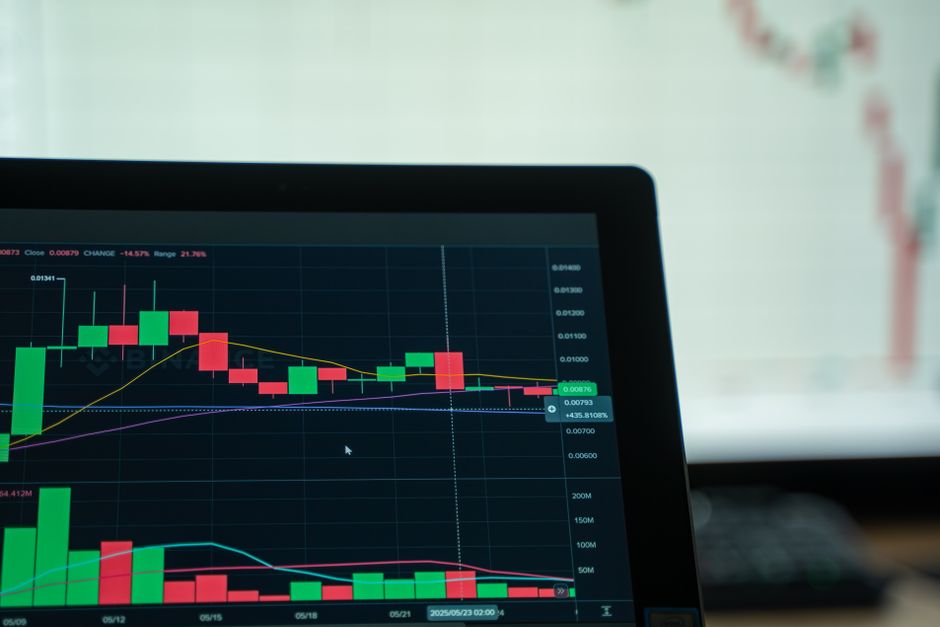
A range can be tall on light volume and narrow on heavy volume, and both combinations turn up regularly. Height records how far price travelled. Volume records how much business was transacted getting there. When the two disagree, the disagreement is the useful part.
A tall range built on thin participation means a small number of orders moved price a long way because very little stood in the way. That says more about absent liquidity than about conviction, and the extremes it produced are not levels anyone defended. A narrow range built on heavy participation means a great deal of business changed hands inside a small area, with both sides content to transact there. Those edges have been genuinely contested even though they sit close together.
The Shape of Volume Across the Period
Volume is nearly always front loaded. The first minutes clear the overnight backlog, and that burst tells you little beyond the fact that the session opened. What happens after it is more informative.
Volume that decays steadily through the rest of the period suggests the early imbalance has been worked through and participants have taken their positions. Volume that stays elevated, or fades and then builds a second hump before the period closes, suggests the disagreement is still live and the range is not a settled thing. The second pattern tends to precede a break with something behind it, because the participants who would drive that break are visibly still present.
Where the Volume Sat Inside the Range
Two ranges carrying the same total volume can distribute it very differently, and the distribution changes what the edges mean. Heavy trade clustered at the high while price refuses to leave the high is absorption. Buyers are being filled by someone willing to sell everything they bring. That is a level with a seller standing at it, and a later break through it means that seller either ran out or stepped away, which is a real event rather than a drift.
Volume concentrated in the middle with light trade at both extremes describes something else, a fair value area with thin edges. Thin edges break easily, which sounds like an advantage until you notice they break back through just as easily, because there is no accumulated business at either one to slow price down.
Judge It Against the Instrument's Own Habit
Raw volume figures mean nothing on their own. A number that is heavy for one instrument is a dead session for another, and the same instrument trades differently in a quiet stretch of the calendar than it does around a busy one. The only comparison worth making is against that instrument's own recent opening periods.
A rough sense is enough. Knowing that today's formation carried noticeably less business than the last several sessions is sufficient to change how much weight the resulting levels deserve, and that is a judgement made by looking rather than calculating. Precision buys very little here.
The Limits of Reading Formation Volume
None of this points a direction. Volume during formation describes the quality of the range, not the way it will resolve, and treating it as a directional signal is a quick route to talking yourself into a trade you had already decided to take.
It is also worth knowing where the figure comes from. An instrument trading across several venues can show quite different totals depending on whether the feed aggregates them, and a comparison is only valid against numbers gathered the same way. Read consistently, formation volume tells you how much to trust the two lines you have just drawn. That is a smaller claim than a signal, and a more durable one.